The Inspection Found Problems. Do I Walk Away?
By Edelio Sanchez
Almost every inspection finds problems. The real question is never whether the report has findings, it is which ones are deal breakers, which ones are just money, and which ones are noise.
I have handed clients reports that ran dozens of pages and watched their face fall. Then we sorted it, and the house was fine. I have also seen two-page reports with one finding on them that I told the client to walk away from. Length tells you nothing.
What is an inspection report actually for?
It is an inventory, not a grade. There is no pass or fail.
A good inspector documents everything they can see, photographs it, and flags anything that is at or near the end of its service life. That includes completely normal wear on a well maintained house. A ten year old water heater is not a defect, it is a ten year old water heater, and it goes in the report because a competent inspector tells you what you are inheriting.
This is why reports read as alarming even on good houses. Thoroughness looks like bad news when you are reading it for the first time at eleven at night.
Which findings actually matter?
I sort every report into three piles before I talk to the client.
Pile one, the ones that change the decision. Structural movement, active water intrusion, a roof that is at the end of its life, major systems that are done, electrical that is unsafe, and anything that affects whether you can insure the house. These are either expensive, hard to scope, or both.
Pile two, the ones that are just money. Deferred maintenance with a clear price. A water heater near the end, a failed seal, a fence section, an old but functioning HVAC. These are negotiable, and they are also predictable, which makes them much less frightening than pile one.
Pile three, the noise. Missing outlet covers, a sticking door, hairline stucco cracks, a loose handrail. This pile is long on every report and it should not drive a decision. Asking a seller to fix nine cosmetic items is how you spend your credibility on nothing.
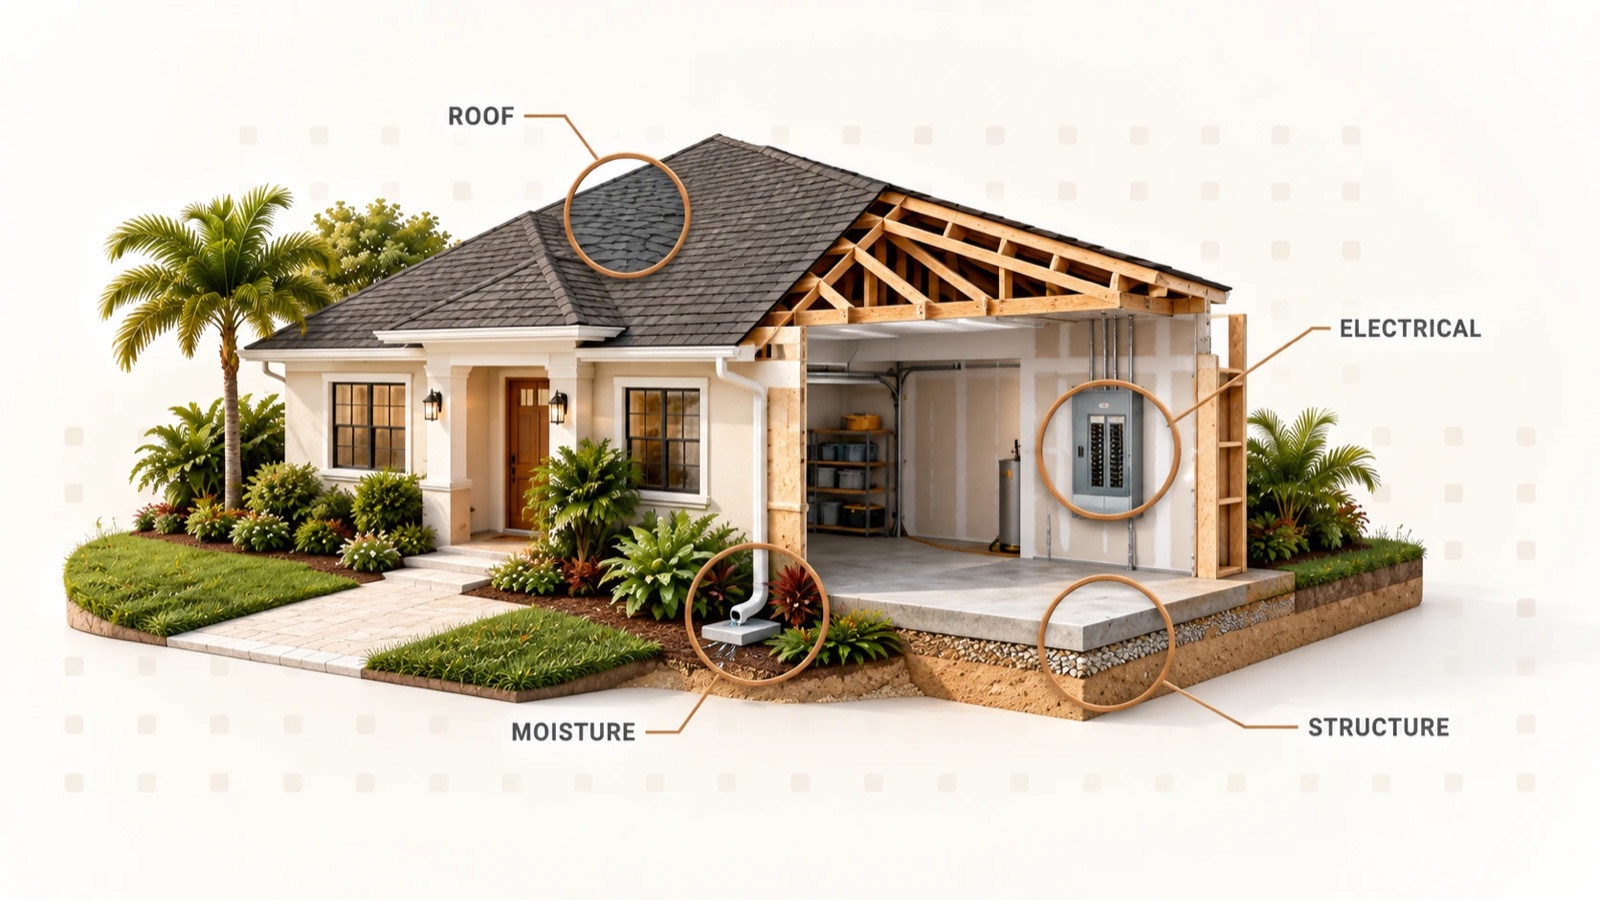
A few things get extra attention in Central Florida specifically: roof age and condition, moisture and drainage around the slab, the age and type of the plumbing, the electrical panel, whether additions and enclosures were permitted, and the separate wood destroying organism inspection. None of that is exotic here. It is just what our housing stock and our climate produce.
The Florida finding that quietly ends deals
Insurability, and it is worth its own section because it catches people by surprise.
If a carrier will not write a policy on the house, or will only write one at a price you cannot carry, your lender will not close the loan. Roof age and condition are the usual culprit. It does not matter how much you love the house or how good your loan is. No insurance, no mortgage.
So when a report flags the roof, the very next call is not to a roofer, it is to an insurance agent for a real quote on that specific house. If you have not read why your Florida home insurance quote came back so highwhy your Florida home insurance quote came back so high/home-insurance-florida, that is the context for this whole problem.
What are my options after the report?
Four, and which ones you actually have depends on your contract.
- Ask the seller to repair specific items before closing.
- Ask for a credit or a price reduction and handle the work yourself.
- Proceed as is, having priced in what you now know.
- Cancel, if you are still inside the inspection period your contract gives you.
Two things to understand about that list. Most Florida resale contracts I see are written as "as is," which means the seller has no obligation to repair anything. Your leverage is not a right to demand repairs, it is your right to walk away inside the inspection period. That is a real difference and it changes how you ask.
And between a repair and a credit, I usually prefer the credit. You choose the contractor, you control the quality, and you are not inheriting the cheapest possible fix done in a hurry by someone the seller found on a Saturday. The honest caveat is that credits are not unlimited. Your loan program caps what the seller can contribute, so a large credit may not fit, and that is a conversation for your lender before you ask for it.
So should I walk away?
Walk when the problem is expensive and the scope is genuinely uncertain. A crack you can price is a negotiation. Movement nobody can explain yet is a different thing, because the number could be anything.
Walk when the house may not be insurable at a price you can carry.
Walk when the seller will not move and you cannot fund the fix without emptying your reserves. Buying a house with nothing left over is how a manageable repair becomes a crisis.
Do not walk over pile three. And do not walk because the report was long.
If the appraisal also came back below your contract price, that is a separate problem with separate options, and I walk through it in my appraisal came in low, what happens now?my appraisal came in low, what happens now?/blog/appraisal-came-in-low.
What I would have you do
Get quotes, not guesses, and start the day the report lands.
An opinion about what a repair costs is worth nothing in a negotiation, and it is worth less than nothing in your own decision. Two real quotes from licensed contractors turn a scary finding into a number, and a number is something you can negotiate or budget or decline.
The catch is that inspection periods are short and contractors are busy. If you wait three days to start calling, you will run out of time and end up choosing between proceeding blind and cancelling out of caution. Neither is a good place to be.
Send me the report. I will sort it into the three piles, tell you which findings I would actually push on, and help you get quotes fast enough to matter. Most of the time the house is fine and the report just needed translating.
Frequently Asked Questions
Get the weekly Central Florida market brief
One short email each week: local market updates, fresh listings before they hit the search sites, and practical tips for buyers and sellers in Central Florida.
No spam. Unsubscribe anytime.